China’s yuan strategy seeks an alternative to the dollar, expert says
Zongyuan Zoe Liu says Beijing may want the yuan to limit sanctions exposure, not replace the dollar as the leading global currency.
By Daniel Okafor · Business Editor
3 min read
China’s yuan strategy is aimed at building a usable alternative to the U.S. dollar rather than taking its place at the center of global finance, according to Zongyuan Zoe Liu, a senior fellow for China studies at the Council on Foreign Relations. That distinction matters because a broader yuan payments network could reduce China’s exposure to U.S. financial sanctions without Beijing accepting the costs and loss of control that Liu associates with reserve-currency leadership.
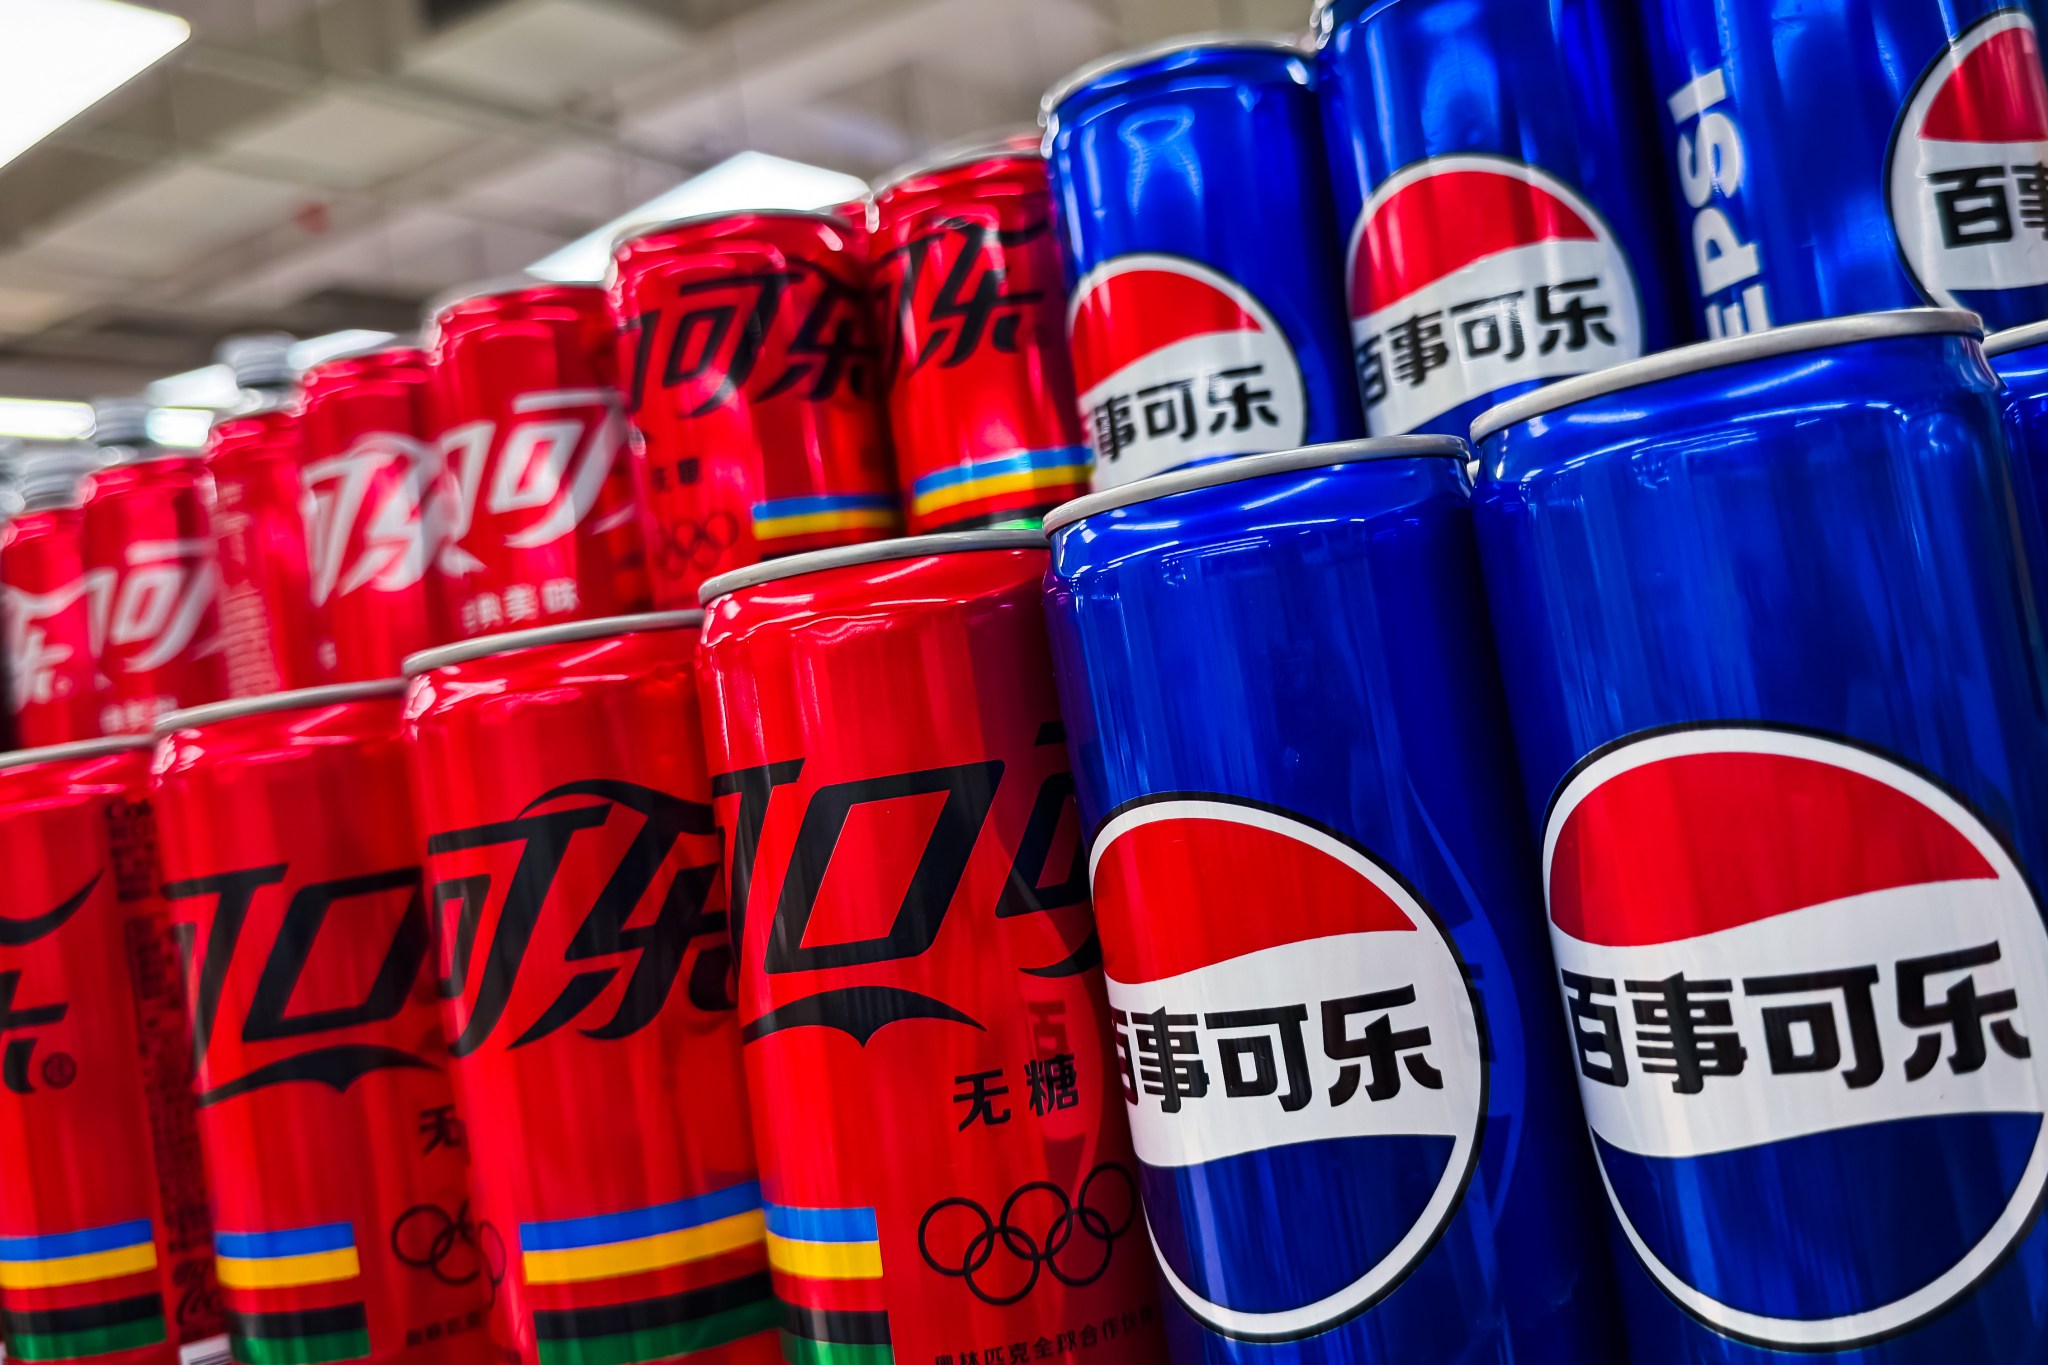
Writing in Foreign Affairs, as reported by Fortune, Liu compared the desired role for the renminbi, another name for the yuan, to Pepsi’s position against Coca-Cola: a viable competitor rather than the market leader. In her analysis, a meaningful second- or third-place currency could weaken the dollar’s effective monopoly and make unilateral U.S. sanctions harder to impose.
Why is China promoting the yuan without seeking to replace the dollar?
Liu’s argument is that a currency capable of replacing the dollar would need open capital markets and a large supply of assets that foreign investors can buy and sell freely. Fortune reported that she sees those conditions as inconsistent with Beijing’s capital controls and its control over capital allocation.
The objective, in Liu’s account, is sanctions resilience. A larger yuan-based system could provide another route for trade and payments if China faced restrictions in dollar-based finance, similar to the isolation Russia faced after its 2022 invasion of Ukraine, Fortune reported. That is an assessment of Beijing’s aims, rather than a stated official policy.
China has expanded infrastructure for yuan payments. Fortune said that, as of June, its Cross-Border Interbank Payment System, or CIPS, had 1,829 participants able to make payments to more than 5,200 banks in 191 countries. The Peterson Institute for International Economics described CIPS as a relative bright spot for the currency’s international use.
CIPS is a clearing and settlement system for cross-border yuan payments, while SWIFT is a global network for banks to exchange payment messages. The systems can be connected: PIIE said CIPS integrated with SWIFT messaging after its 2015 launch. Its growth therefore does not, by itself, show that international payments have shifted wholesale away from dollar-based finance.
What do the figures say about the yuan’s global role?
The indicators remain mixed. PIIE said the yuan’s share of SWIFT payment volume climbed to 4.7% in July 2024 before falling to 2.75% by May 2026, making it the sixth-most-used payments currency by that measure. It also reported that 72% of China’s trade was still settled in other currencies.
Foreign demand for yuan assets is another constraint. Fortune reported that foreign investors held 1.6% of China’s bond market in March, compared with 27% of the U.S. bond market. Liu argued that without a much deeper pool of freely tradable yuan assets, the currency cannot approach the dollar’s role.
PIIE reported that President Xi Jinping called in 2023 for a strong currency with wide use in trade, investment and foreign-exchange markets, including global reserve-currency status. Liu’s analysis suggests that, in practice, China may pursue wider yuan use while preserving the controls that limit its path to dollar replacement.
This story draws on original reporting from Fortune.