10-year Treasury yield above 5% raises borrowing-cost and market concerns
The 10-year Treasury yield has moved above 5%, but economists and investors disagree on whether the rise signals strong growth or mounting risk.
By Maya Lindqvist · Senior Technology Correspondent
3 min read
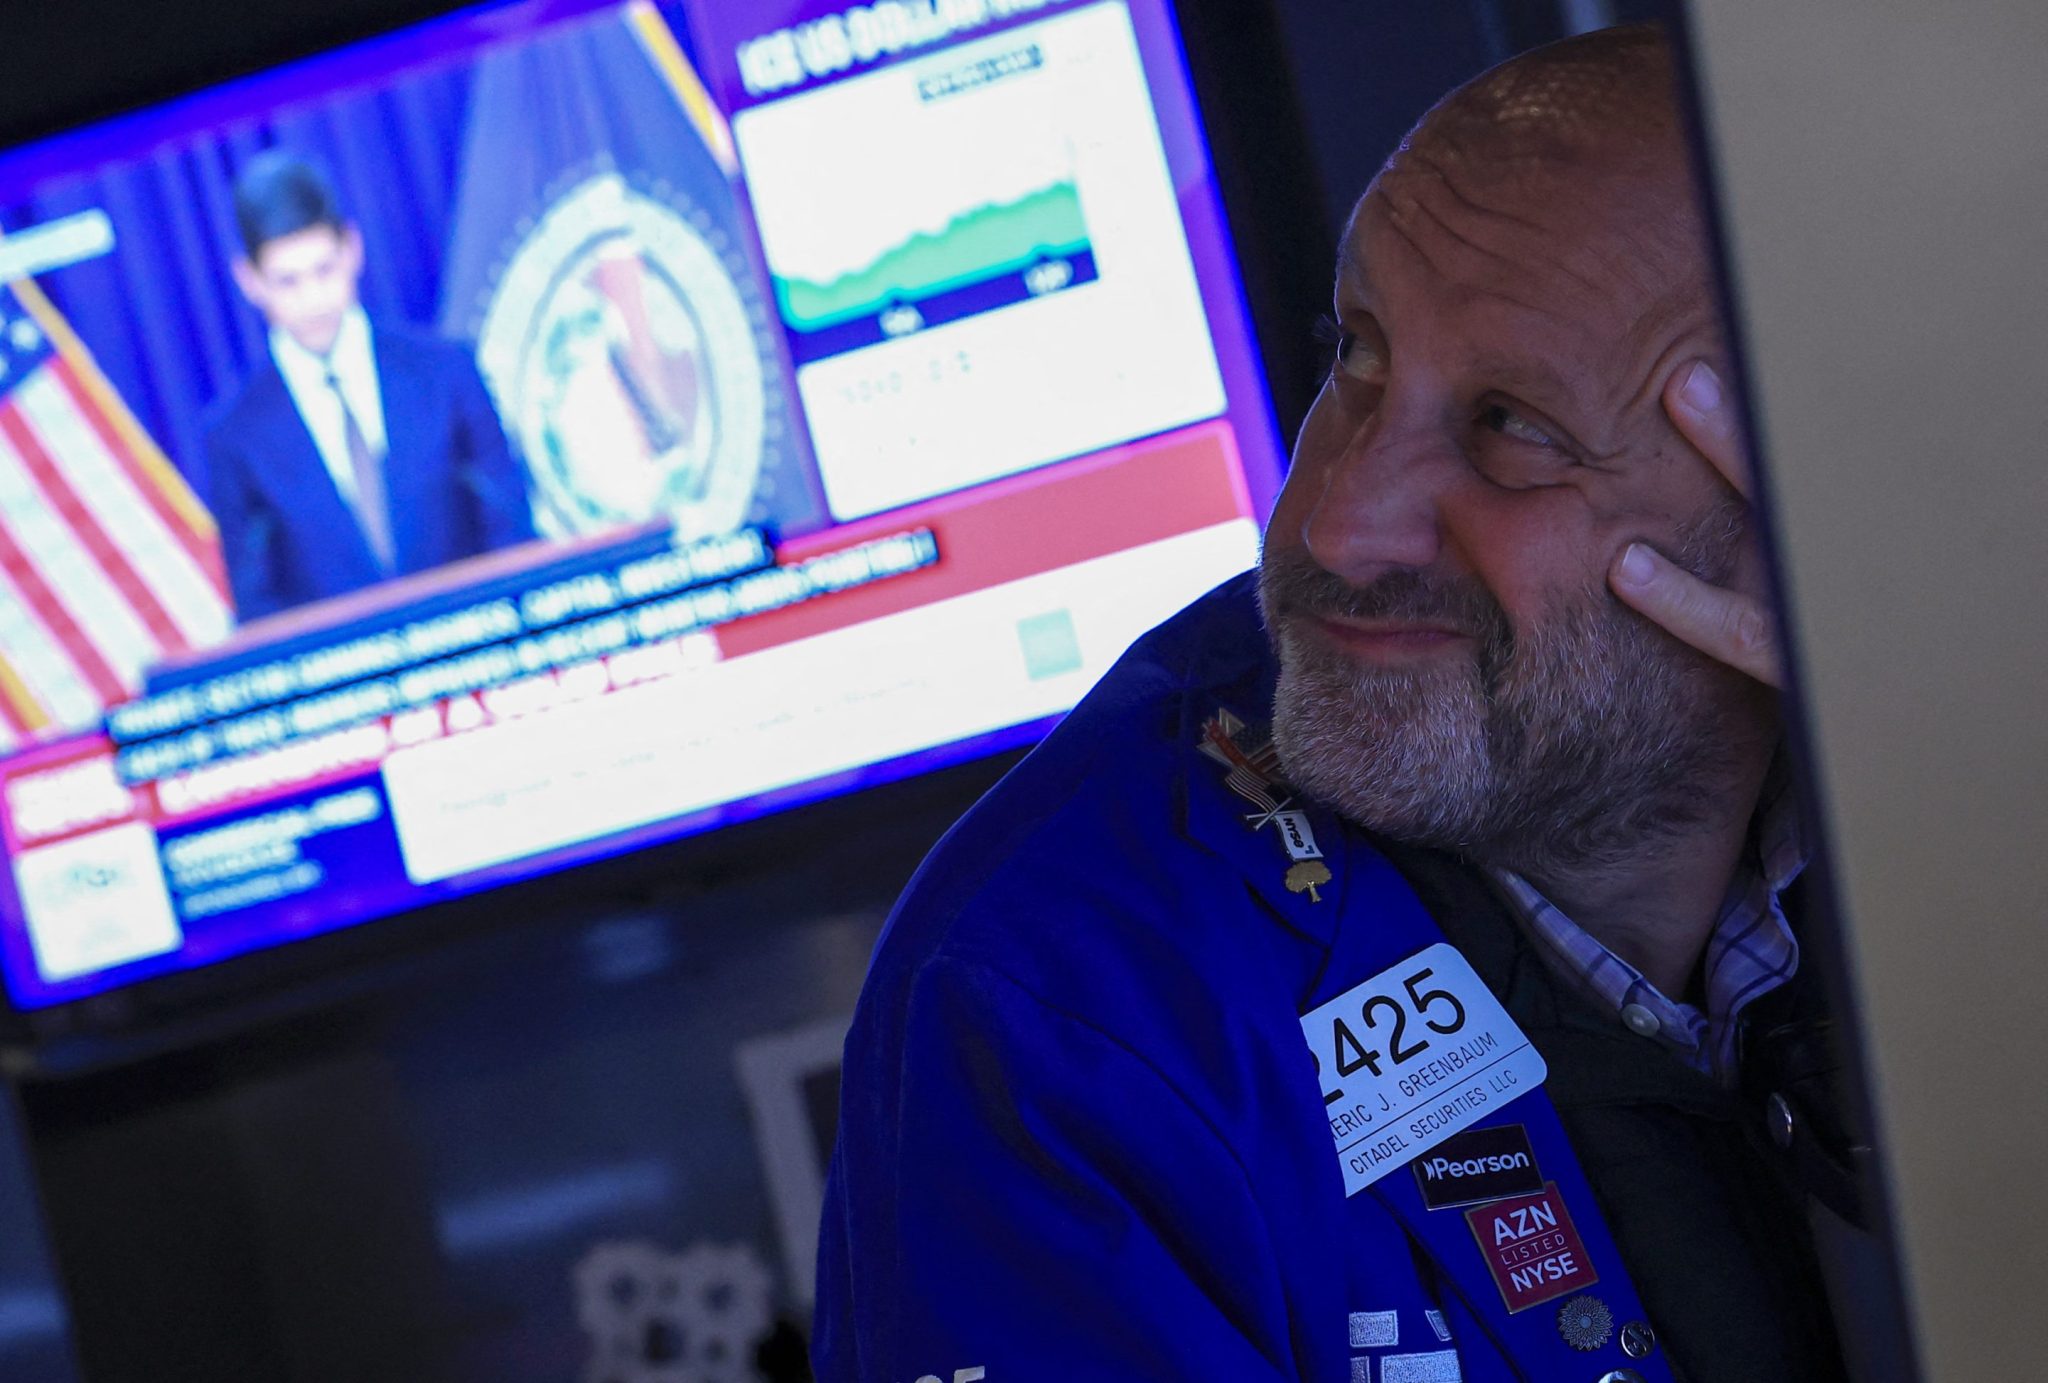
The 10-year Treasury yield 5% debate has returned after the benchmark yield moved above that level in September. Fortune reported it reached 5.21%, its highest reading since 2007, while Reuters reported that the move has renewed concern about borrowing costs and pressure on stock valuations. The level is closely watched, but analysts caution that its cause and staying power matter more than the round number.
Treasury yields are a reference point for borrowing across the economy. Fortune reported that the average 30-year mortgage rate rose to 7.45% alongside the yield increase; higher government borrowing costs can also feed into consumer and business lending rates. For borrowers and savers, interest rates are the price paid to use money or the return received for lending it.
Why does a 5% 10-year Treasury yield matter?
A Treasury bond is a loan to the U.S. government. Its yield is the annual return investors receive, and yields rise when bond prices fall. When investors require a higher return to lend for 10 years, that raises the benchmark return against which many loans and investments are judged, according to Fortune.
It also changes the comparison between stocks and safer government debt. Reuters quoted BlueBay Asset Management strategist Mike Bell as saying 5% is a psychological marker rather than an automatic trigger for market turmoil. Bell said the relevant comparison includes Treasury yields and the earnings yield available from stocks.
The constructive case: growth can support higher yields
One explanation is that investors expect resilient growth, firm corporate earnings and Federal Reserve policy rates to remain high for longer. Under that view, a higher long-term yield reflects a stronger economy rather than an abrupt loss of confidence in U.S. debt, Fortune reported.
Fortune cited Jefferies analysts who argued that broad earnings growth could help equities withstand higher long-term rates. The same report pointed to large planned technology investment, including AI spending, as part of the growth case. Reuters also reported JPMorgan analysts’ view that structural changes in the economy could make traditional interest-rate effects less restrictive, though that remains an analyst view rather than a fixed market rule.
The risk case: investors demand more compensation
The more troubling explanation is a rising term premium: the added return investors demand for holding long-dated debt amid uncertainty over inflation, deficits and the volume of bonds coming to market. Fortune reported weak demand at a five-year Treasury auction and cited concerns that federal borrowing, war-related spending and corporate debt issuance tied to AI investment could test demand for bonds.
Morningstar likewise identified government-debt concerns, corporate borrowing and oil-related inflation pressure as forces lifting yields. If those concerns, rather than growth, are driving the move, higher yields can weigh on household and business borrowing, restrain economic activity and reduce the value investors place on future corporate earnings.
What investors are watching next
- The speed of further yield increases and whether yields remain elevated for an extended period.
- Inflation and oil-price pressure, which can alter expectations for Federal Reserve policy.
- Demand at Treasury auctions and concerns about the supply of federal debt.
- Corporate earnings, which help determine whether stocks can absorb higher financing costs.
Higher yields also bring an offset for bond buyers. Morningstar reported that new investors can receive more income from bond payments, while that income may cushion additional price declines. Existing bondholders and bond-fund investors can still face losses as prices fall, especially before their holdings mature.
The evidence so far does not establish 5% as a universal breaking point. A durable rise driven by inflation and demand worries would carry different risks from an orderly increase tied to growth and expected policy rates.
This story draws on original reporting from Fortune.